ETFs are often seen as an easy way to spread money across many companies. Instead of buying one stock, an investor can buy one ETF and get exposure to hundreds of businesses at once. This sounds like strong diversification.
But there is an important detail that many investors miss.
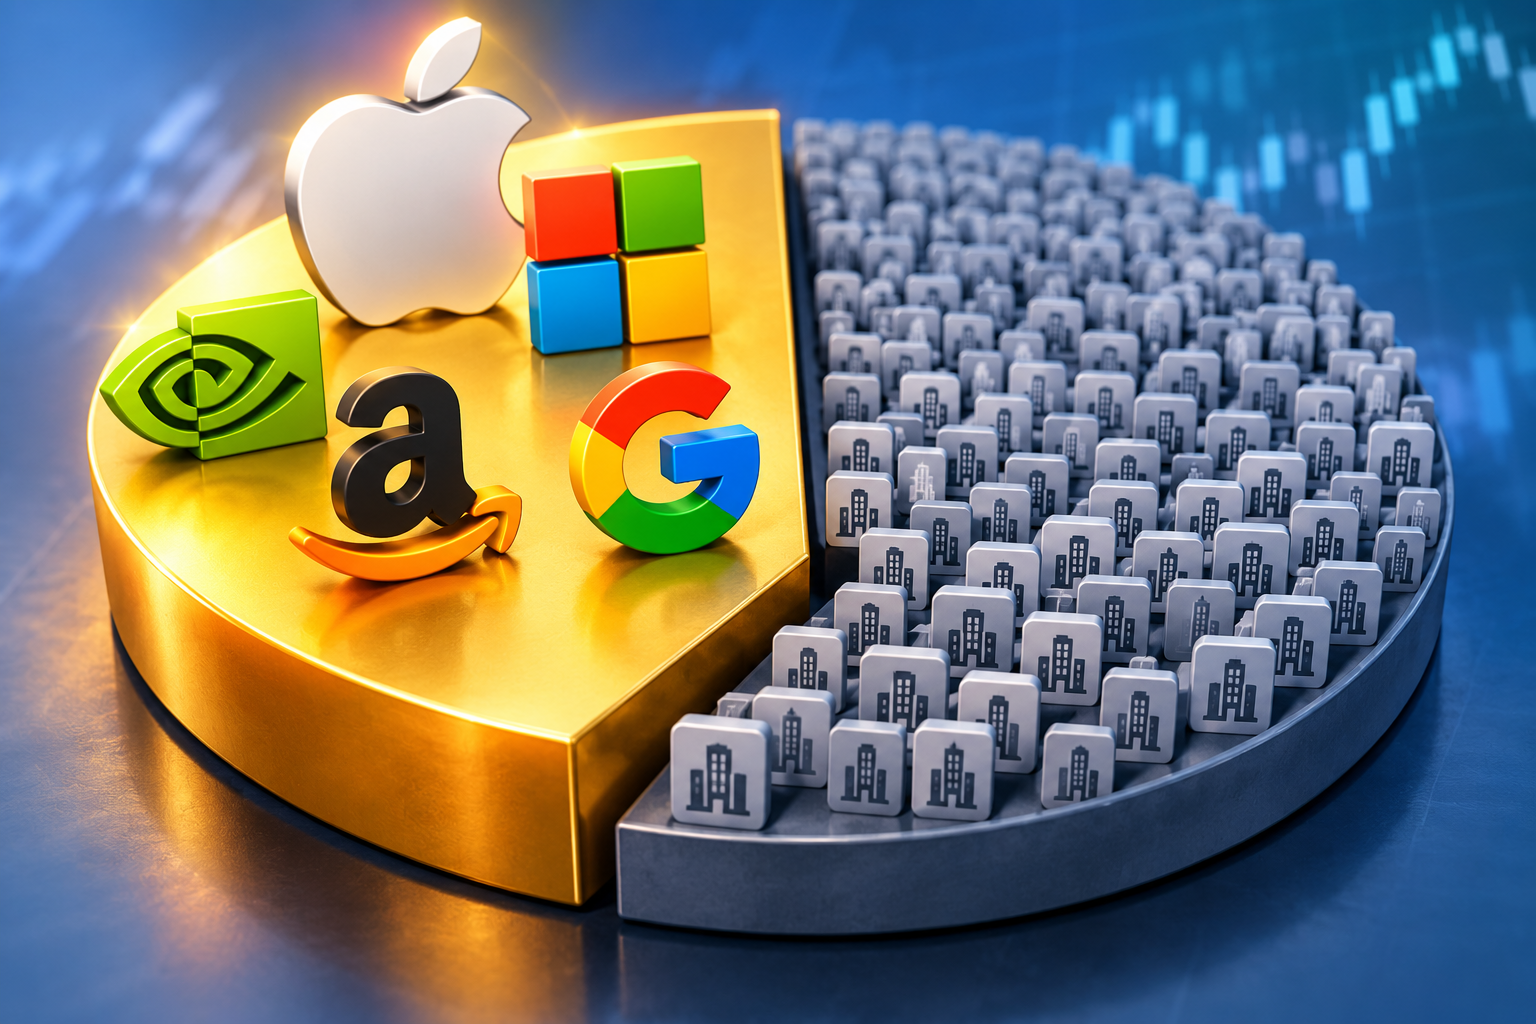
An ETF can hold hundreds of stocks and still have a large part of its value tied to just a few companies. In some broad market ETFs, the five largest stocks can make up a large share of the total portfolio.
This does not mean the ETF is poorly built. It simply means that the number of stocks inside an ETF does not tell the full story.
The real question is not, “How many stocks does this ETF own?” A better question is, “How much of my money depends on its largest stocks?”
That difference matters because a portfolio with 500 stocks may look very different from a portfolio with 500 stocks that have equal weights.
The Five-Stock Example
Consider a simple ETF with 500 stocks. It may look highly diversified because an investor has exposure to 500 different companies.
Now look at the weights of its largest holdings.
| Holding | Weight |
|---|---|
| Stock A | 8% |
| Stock B | 7% |
| Stock C | 6% |
| Stock D | 5% |
| Stock E | 4% |
| Top 5 | 30% |
| Other 495 stocks | 70% |
The ETF still owns 500 companies. However, the five largest names account for 30% of the entire portfolio.
The other 495 stocks share the remaining 70%.
This tells us something important. The ETF has a large number of holdings, but its returns may depend heavily on a small group of major companies.
If those five stocks rise sharply, they can have a major effect on the ETF. If they fall at the same time, they can also pull the ETF down, even when many of the other stocks perform well.
Why Market-Cap Weighting Matters
One major reason for this effect is the way many popular stock indexes are built.
A large number of major indexes use market-cap weighting. Under this method, a company receives a larger weight when its total market value is larger.
The idea is simple.
A company with a very large market value gets more space in the index than a company with a small market value. An ETF that follows that index then holds more of the larger company.
This can create a powerful cycle.
Company rises → market cap increases → index weight increases → ETF owns more of it.
As successful companies become larger, their share of the index can also grow. Over time, this can make a broad index more dependent on its biggest winners.
There is no need for the fund manager to make an active decision to place a large bet on one company. The index rules can create that exposure on their own.
More Stocks Do Not Always Mean More Diversification
It is easy to assume that 500 stocks must be safer than 50 stocks.
That is not always true.
Imagine one ETF has 500 stocks, but its largest 10 companies account for a very large share of its value. Another ETF has 100 stocks with a much more even spread across its holdings.
The first ETF has more stocks. Yet the second ETF may have less concentration.
This is why the number of holdings can sometimes give investors a false sense of security.
Diversification is not only about owning different names. It is also about how much money sits in each name.
If one stock has a 10% weight, a 10% fall in that stock has a much larger effect on the ETF than a 10% fall in a stock with a 0.2% weight.
The same idea applies to the largest five or ten companies.
Sector Concentration Adds Another Layer
Company concentration is only one part of the story.
The largest companies in an ETF may also come from the same sector. If several of the top holdings belong to technology, for example, the ETF may carry a strong technology bias.
That means an investor could own hundreds of companies but still have a large part of the portfolio exposed to the same economic force.
Technology stocks may react to changes in interest rates, business investment, artificial intelligence demand, chip demand, or software spending. If several large holdings depend on similar factors, they may move in the same direction.
This creates factor concentration.
So there can be three different levels of concentration: one company, one sector, and one common economic factor.
An ETF can appear broad at the first level while still remain quite concentrated at the second and third levels.
Look Beyond the Holdings Count
Investors should look at more than the headline number of stocks before they decide that an ETF is highly diversified.
The top-five weight is a useful first check. It shows how much of the ETF sits in its five largest positions.
The top-ten weight can offer an even wider view. If the top 10 stocks account for a very large share of the fund, the ETF may depend heavily on a small group of companies.
Another useful measure is the Herfindahl-Hirschman Index, or HHI. It provides a more formal way to measure concentration. A higher HHI means the portfolio has more weight in fewer holdings.
Investors can also check sector concentration. This shows whether a large part of the ETF sits in one area of the market.
There is also the idea of the effective number of stocks. This asks a useful question: how many equally weighted stocks would create a similar level of concentration?
That figure can give a better sense of the ETF’s real diversification than its simple holdings count.
Why Concentration Is Not Always Bad
High concentration does not automatically make an ETF a bad investment.
There is a reason market-cap indexes give more weight to large companies. The largest companies represent a major part of the overall market. A market-cap-weighted ETF is meant to reflect that market rather than give every company the same share.
If the largest companies continue to perform well, investors in a concentrated index can benefit.
The issue is not that concentration exists. The issue is whether an investor understands it.
Someone who buys a broad market ETF for simple market exposure may be comfortable with this structure.
Another investor may want a more even spread across companies. That person may prefer an equal-weight index or another ETF with lower concentration.
The right choice depends on the investor’s goal.
Equal Weight Can Create a Different Picture
An equal-weight ETF uses a different approach.
Instead of giving much more weight to the largest companies, it tries to give each company a similar share.
This can reduce the effect of a few giant stocks on the overall portfolio.
For example, a major company would not dominate the ETF simply because its market value is far larger than the rest.
But equal weighting also has trade-offs. It can give more weight to smaller companies than a market-cap index does. It may also need more frequent changes to keep the weights close to equal.
So there is no perfect method.
Market-cap weighting, equal weighting, and other approaches each create a different type of exposure.
The Bigger Lesson for ETF Investors
The word “diversified” should never be the end of the research.
An ETF can own 500 stocks and still have a large dependence on five or ten major companies. The five-stock example makes this clear: 30% of the portfolio can sit in just five holdings, while the other 495 stocks account for 70%.
That does not make the ETF fake or poorly diversified. It simply shows why the number of holdings is not enough.
Before buying an ETF, investors should look at the top holdings, their combined weight, sector exposure, and the overall concentration of the portfolio.
The simple rule is worth remembering:
Do not ask only how many stocks an ETF owns. Ask how many stocks actually drive its returns.
That is the difference between nominal diversification and economic diversification. An ETF can have hundreds of names on its list while a small group of giants still has a powerful effect on what investors experience.
ALSO READ: When a Fund Becomes Too Popular