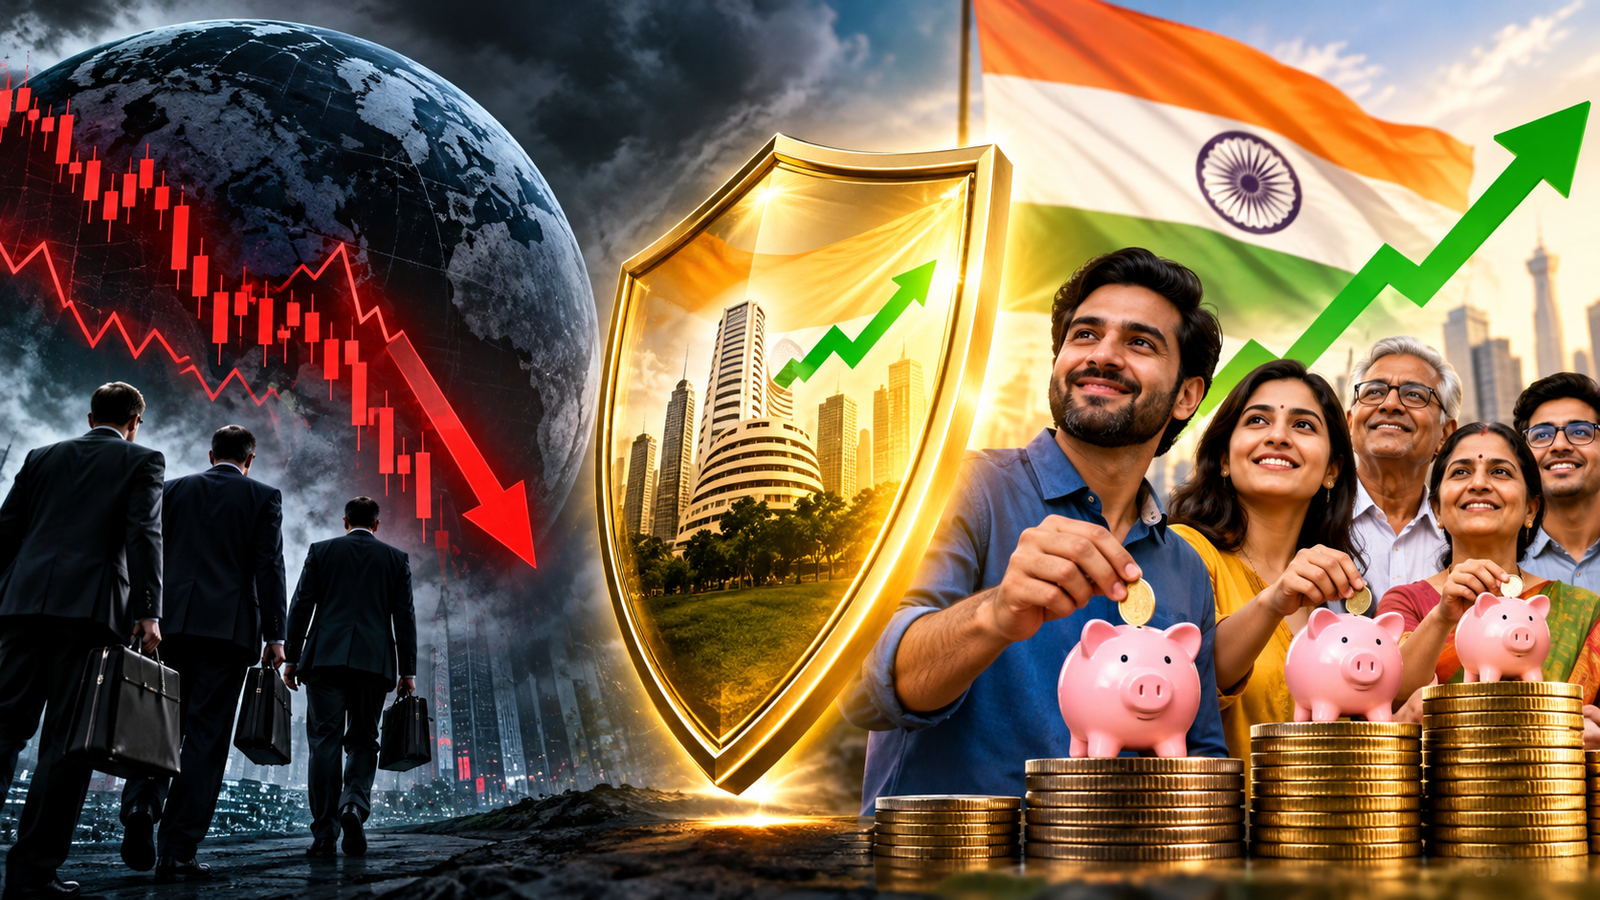
India’s stock market has a support system that was much smaller a decade ago. Millions of local investors now put money into mutual funds every month. This steady flow has helped the market absorb periods of foreign selling.
The latest data gives a clear picture. In August 2026, monthly SIP contributions reached a record ₹32,297 crore. Equity mutual funds also received ₹29,329 crore, up from ₹24,697 crore in July. Equity funds have now seen net inflows for 66 straight months.
This matters because foreign investors can change their positions very fast. A rise in US bond yields, a stronger dollar, higher oil prices or a sudden rise in global risk can lead foreign funds to pull money from emerging markets.
Domestic investors work in a different way. A large part of their money enters through SIPs. These plans usually follow a fixed monthly schedule. That creates a more stable source of demand for Indian equities.
Retail Investors Stay With the Market
The most striking part of the latest data is the strength of retail participation despite market uncertainty.
SIP contributions rose 1.1% in August to ₹32,297 crore. The number of contributing SIP accounts crossed 10 crore, at 10.02 crore, for the first time. Total SIP accounts stood at 10.62 crore at the end of August. SIP assets under management rose to ₹18.62 lakh crore, from ₹18.20 lakh crore in July.
The industry also added 66.39 lakh new SIPs in August, while 53.82 lakh SIPs were closed, matured or discontinued. This shows that fresh participation remained higher than exits.
For the broader mutual fund industry, assets under management rose 1.5% to ₹87.08 lakh crore at the end of August. The total number of mutual fund folios also rose by 26.54 lakh during the month to 28.35 crore.
These numbers point to a major change in the Indian market. Household savings now have a much larger role in equity markets. Local investors are no longer a small part of the market. Their regular flows can provide support when foreign capital moves out.
Domestic Institutions Absorb Foreign Selling
The change becomes clearer when we look at domestic institutional investors, or DIIs.
In FY26, DIIs bought ₹8.09 lakh crore of Indian equities. During the same period, foreign institutional investors sold ₹1.81 lakh crore. The domestic purchases were about 347% higher than the foreign sales.
This does not mean every rupee sold by a foreign investor goes directly to a domestic buyer. Markets do not work in such a simple way. But the numbers show that domestic institutions now have enough capital to absorb a large part of the pressure from overseas investors.
There has also been a long-term shift in market ownership. The share of mutual funds in the free-float market capitalisation of NSE-listed companies rose to about 23% in March 2026, from about 15% in March 2021. At the same time, the foreign investor share declined.
This gives Indian markets a broader domestic base than they had in the past.
Small and Mid Caps Get Strong Demand
Another important part of the story is where domestic investors are putting their money.
In August, small-cap funds received ₹7,973 crore. Mid-cap funds received ₹6,989 crore, while flexi-cap funds received ₹5,059 crore. Large-cap funds, however, saw an outflow of ₹1,147 crore.
The small-cap figure was a record. Mid-cap flows also reached a record level.
This tells us that domestic investors are not simply buying the largest companies that dominate major indexes. A large share of their money is also going into smaller and mid-sized businesses.
That creates an important difference between domestic and foreign flows. Foreign investors often have a much larger presence in major companies. Domestic mutual fund flows can have a greater effect on mid-cap and small-cap stocks.
As a result, strong domestic flows can support the wider market even when pressure remains on some large companies.
Foreign Investors Still Matter
The domestic flow story does not mean foreign investors have become unimportant.
Foreign money remains a major part of Indian financial markets. When global conditions change, their decisions can still have a strong effect on stocks, the rupee and market sentiment.
The recent data shows this clearly. Foreign portfolio investors, or FPIs, bought more than ₹20,200 crore in July and about ₹29,630 crore in August. But they turned sellers again in September. In the first week of September alone, they withdrew ₹7,443 crore from Indian equities.
By September 11, the withdrawal for the month had reached ₹13,138 crore. The fresh selling came as crude prices rose, US bond yields moved higher and the dollar stayed firm.
This is the key point. Domestic investors can soften the effect of foreign selling, but they cannot remove the global forces that cause that selling.
Why SIPs Are Different
One reason for the strength of domestic flows is the nature of SIP investment.
An investor who puts a fixed amount into a mutual fund every month does not need to make a fresh decision each time the market falls. The money enters the market according to a plan.
This can create a steady demand base during periods of uncertainty.
It also means that a short-term market fall does not always lead to a large fall in domestic investment. For many investors, the focus remains on a much longer period.
This behaviour is very different from a global fund that may reduce its exposure to India because of changes in interest rates, currency moves or risk levels across several countries.
That difference gives India a useful cushion.
But There Is a Valuation Risk
There is another side to the story.
Strong domestic flows can support stock prices, but flows alone cannot decide the long-term value of a company. Earnings, cash flow, debt and business growth still matter.
The strong preference for small and mid-cap funds also deserves attention. These parts of the market can see larger price swings than large companies. Strong demand can push prices higher, but a change in sentiment can also create sharper falls.
The August data showed that investors continued to prefer these areas even as global risks remained high. That shows confidence, but it also means investors need to accept the higher risk that comes with these segments.
The Bigger Change in India’s Market
The most important development is not one month of strong SIP flows. It is the gradual rise of domestic capital over several years.
India’s market now has a much larger pool of household savings that can enter equities through mutual funds. This reduces the market’s dependence on foreign capital at the margin.
That does not make India immune to global shocks. A major rise in oil prices, a sharp dollar rally, higher US yields or a global liquidity crisis can still affect Indian assets.
However, the impact can be different from the past because local investors now provide a much stronger base.
The recent numbers make that change visible. ₹32,297 crore entered mutual funds through SIPs in August. Equity mutual funds received ₹29,329 crore. Small-cap funds received ₹7,973 crore, while mid-cap funds received ₹6,989 crore. At the same time, DIIs had a record ₹8.09 lakh crore of purchases in FY26 against ₹1.81 lakh crore of foreign selling.
A Cushion, Not a Shield
The retail-investor resilience story is therefore real, but it needs the right context.
Domestic money is helping India absorb foreign selling. SIPs provide a steady source of capital. Mutual funds have a larger role in the market. DIIs have become strong enough to offset a large amount of foreign selling at the aggregate level.
But global risk has not disappeared.
September has already shown how quickly foreign flows can change after two months of strong FPI purchases. The test for India will come when global pressure lasts for a much longer period.
For now, the message from domestic investors is clear: they continue to put money into Indian equities despite volatility. That steady demand has changed the structure of the market and has given Indian stocks a stronger domestic support base.
The bigger question is how long that support can remain strong if global risks rise sharply or if domestic valuations move far ahead of company earnings. That will decide whether domestic flows merely cushion global shocks or become a lasting force that changes how Indian markets respond to them.