Money is a part of our daily life. We need it to buy food, pay bills, travel, take care of our families and meet our needs. We also need money to enjoy life and prepare for the future. But many people do not know where their money goes each month. They earn money, spend it on different things and then have very little left by the end of the month.
This can happen even when a person has a good income. The main problem is often not how much money they earn. It is how they use that money.
A simple money system can help solve this problem. It gives every part of your income a clear purpose. It helps you decide how much to spend, how much to save and how much to invest. It also helps you prepare for sudden costs and avoid unnecessary debt.
You do not need to be rich or have expert knowledge of money to use this system. You only need a clear plan and the habit of follow it. The aim is to make your money easier to manage and help you feel more in control of your life.
Understand the Four Main Jobs of Money
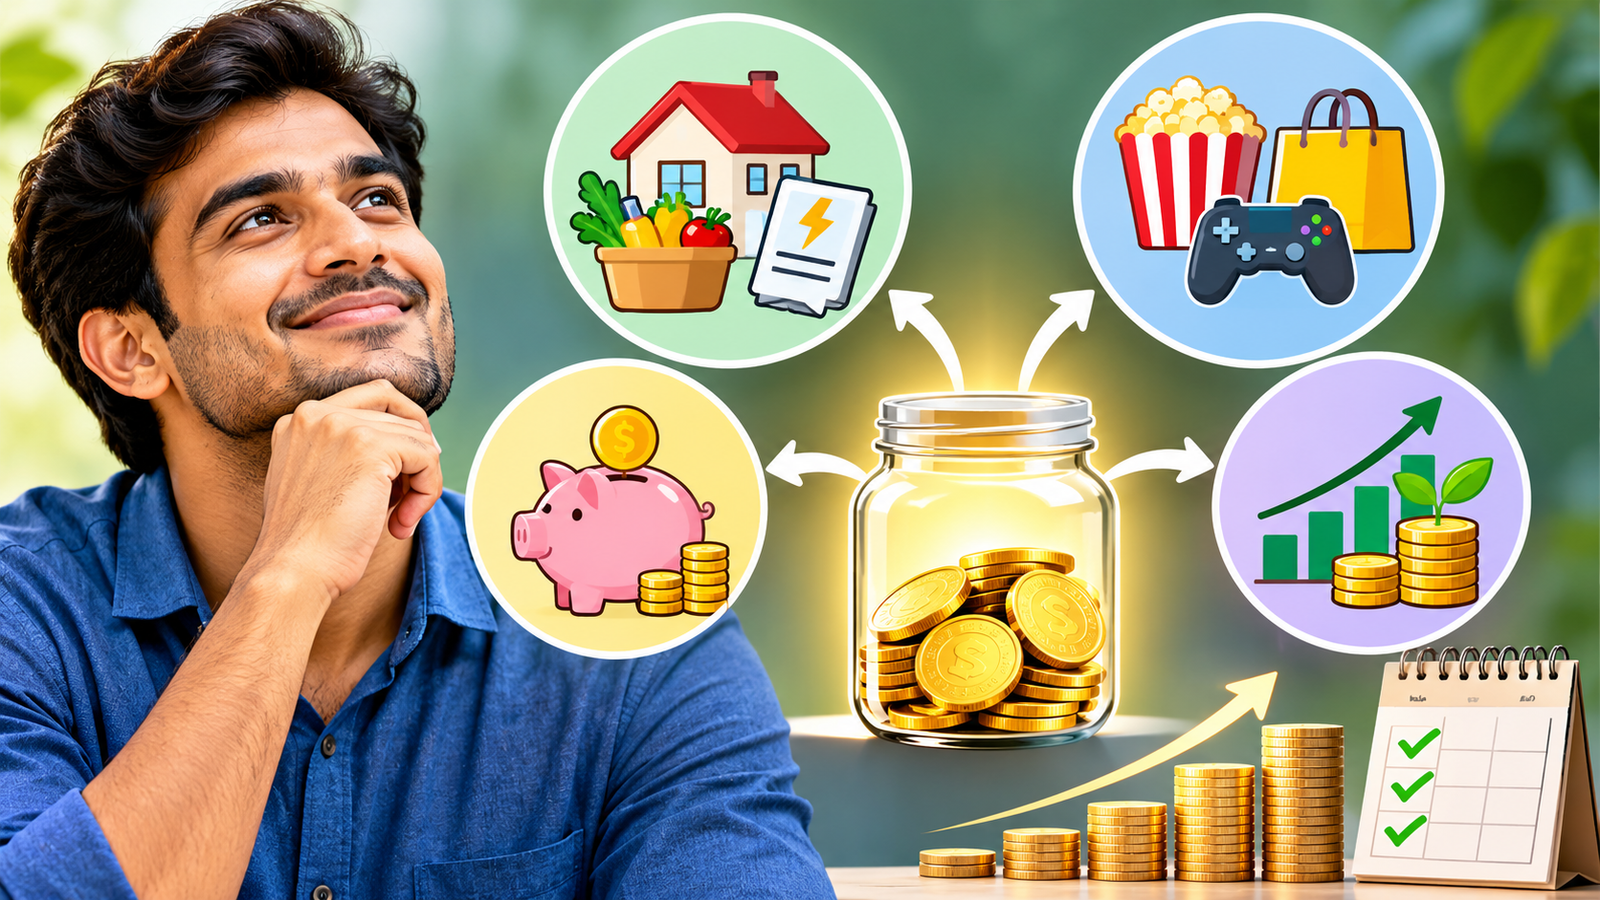
The first step is to understand that your money has four main jobs. These are your needs, your wants, your savings and your investments. Each one has a different purpose, and all four are important.
A simple way to divide your monthly income is the 50-30-10-10 rule. This means you use 50% of your income for needs, 30% for wants, 10% for savings and 10% for investments.
Let us take an example. Suppose you earn ₹40,000 every month. You can use ₹20,000 for your needs, ₹12,000 for your wants, ₹4,000 for savings and ₹4,000 for investments. This gives every rupee a clear purpose.
These numbers are only a basic guide. You do not have to follow them exactly. If your rent or family costs are high, you may need more than 50% for your needs. You can change the amounts based on your income and daily costs.
The most important thing is to have a plan before you spend your money.
Understand Your Needs
Needs are the things you must pay for to live a normal life. These are costs that you cannot easily avoid. They include rent, food, electricity, water, transport, basic clothes and other important household bills.
For example, if you pay ₹8,000 for rent, ₹5,000 for food, ₹2,000 for transport and ₹5,000 for other basic costs, your total needs come to ₹20,000.
These costs should come first in your money plan. You must make sure that you have enough money for them before you spend on things that are not necessary.
It is also important to know the difference between a need and a want. A basic phone may be a need, but the latest expensive phone may be a want. Food is a need, but a costly meal at a restaurant is usually a want.
When you understand this difference, it becomes easier to make better choices with your money.
Understand Your Wants
Wants are the things that make life more fun and comfortable. They are not always necessary, but they can make you happy. These may include eating out, shopping, movies, trips, hobbies, games and other forms of entertainment.
In the 50-30-10-10 system, 30% of your income goes towards wants. If your monthly income is ₹40,000, this gives you ₹12,000 for these costs.
You do not have to stop all fun activities to save money. A good money system should also allow you to enjoy your life. The key is to set a limit and stay within it.
For example, you may decide to spend ₹3,000 on food outside the home, ₹2,000 on shopping and ₹2,000 on entertainment. You can use the rest for other personal choices.
The purpose of this limit is simple. It helps you enjoy your money without waste or stress.
Save Money for Your Future
Savings are an important part of a good money system. Savings are the money you keep for future needs and goals. You may need this money for a medical bill, a family need, a home repair, a course or another important purpose.
In our example, 10% of ₹40,000 is ₹4,000. You can move this amount to your savings account every month.
Do not wait until the end of the month to see how much money is left. You may spend most of your income before that time. Instead, set aside your savings as soon as you receive your salary.
This simple habit can help you save money without much effort. Over time, even small amounts can grow into a useful sum.
You should also keep your savings separate from the money you use for daily costs. This makes it easier to protect your savings and avoid the need to use them for every small purchase.
Invest Money to Build Wealth
Savings help you protect your money, while investments can help your money grow over time. When you invest, you put money into an asset with the aim of earn a return in the future.
In the simple money system, 10% of your income goes towards investments. If you earn ₹40,000 per month, this means ₹4,000 can go towards this goal.
You can learn about options such as index funds, mutual funds, retirement plans and other suitable long-term assets. Each option has its own risks, costs and rules. You should understand these before you put your money into them.
It is also important to know that investments do not always give a profit. Their value can rise or fall, and some investments carry more risk than others.
Do not invest money that you may need very soon. First, take care of your basic needs, emergency savings and costly debt. Then choose investments that match your goals, income and comfort with risk.
The main idea is to invest with care and stay patient. Wealth often takes many years to build.
Create Separate Accounts for Your Money
One simple way to manage money is to keep it in separate accounts or clear money groups. When all your money stays in one account, it can be hard to know how much you can spend.
You can start with four main accounts or money groups.
Your first account is for income. This is where your salary or business income arrives. Your second account is for daily costs. You use it for food, bills, travel and other normal expenses.
Your third account is for savings. This money is for future needs and emergency costs. Your fourth account is for investments. This money is for your long-term financial goals.
You do not need four bank accounts if that is not easy for you. You can also use one bank account with a clear record of each amount. The important thing is to know which part of your money has which purpose.
This method helps you avoid the mistake of spend money that you have already set aside for another need.
Pay Yourself First
Many people use their salary to pay bills, shop, eat out and meet other costs. At the end of the month, they save whatever money remains. The problem is that there may be very little left.
A better method is to pay yourself first. This means you set aside money for savings and investments as soon as your income arrives.
For example, if your salary is ₹40,000, you can first move ₹4,000 to savings and ₹4,000 to investments. You then use the rest for your needs and wants.
This method gives your future goals the same level of care as your daily costs. It also helps you build a regular saving habit.
If possible, set up an automatic bank transfer on the day you receive your salary. This way, you do not have to remember the task each month.
Build an Emergency Fund
Life does not always go as planned. You may lose your job, face a medical cost, need to repair your home or deal with another sudden expense. These events can cause stress if you do not have money set aside.
An emergency fund is money that you keep for such problems. It is not meant for shopping, holidays or normal monthly costs.
Your first goal should be to save enough money to cover one month of essential expenses. After that, try to build a fund that can cover three to six months of essential costs.
For example, if your basic monthly costs are ₹20,000, a three-month emergency fund would be ₹60,000. A six-month fund would be ₹1,20,000.
Keep this money in a safe place where you can access it when needed. Avoid putting your full emergency fund into risky assets, as you may need it at a time when the market value is low.
You do not have to build the full fund at once. Start with a small amount and add to it every month.
Clear High-Interest Debt
Debt can make it harder to manage your money. Some loans have very high interest costs, which means you pay much more than the amount you first borrowed.
Credit card debt and high-interest personal loans are common examples. If you do not clear these debts on time, the interest can grow and take up a large part of your income.
Start by list your debts, their interest rates and the amounts you owe. Make the required payments on time and try to pay extra towards the debt with the highest interest rate.
Once you clear one debt, you can use the extra money to pay the next one.
It is important to understand that not all debt is the same. Some loans may have lower interest rates and a clear purpose. But costly debt should be a priority because it can slow down your financial progress.
Before you focus on large investments, take care of debt that costs you a lot of money.
Start Investing with a Clear Plan
Once you have a basic emergency fund and a plan for your expensive debt, you can focus more on long-term investments.
You do not need a large amount of money to start. What matters is that you understand the product and invest an amount that you can afford.
You can explore diversified index funds and mutual funds. These may offer a way to invest in many companies through one product. You can also look at suitable retirement plans or pension products for your future needs.
Before you choose any investment, learn about its risk, fees, tax rules and time period. Do not invest just because a friend or a social media post says that a product will make you rich.
Avoid the idea of quick profits. A good investment plan should match your personal goals and allow you to stay calm when the market rises or falls.
Review Your Money Every Month
A money system works best when you check it on a regular basis. You do not need to spend hours on this task. Just set aside 20 to 30 minutes once a month.
First, check how much money you earned. Then look at your expenses and see if you stayed within your limits. Check how much you saved and invested. Also, see if you made progress on your debt.
If you spent more than planned, try to understand why. Perhaps your food costs were higher, or you made an unplanned purchase. Do not feel bad about every mistake. Use the information to make a better plan for the next month.
You should also check your bank balance, savings and investments. This gives you a clear view of your financial position.
A monthly review helps you find small problems before they become big ones. It also shows you whether your money habits are better than they were a few months ago.
Understand Your Net Worth
Your bank balance does not show your full financial position. To understand your real financial position, you should know your net worth.
Net worth means the value of everything you own minus the money you owe to others.
The formula is simple:
Net Worth = Assets – Liabilities
Assets are things that have value. These may include cash, savings, investments, property and other valuable items.
Liabilities are the amounts you owe. These may include home loans, car loans, personal loans and credit card debt.
For example, if your total assets are worth ₹5,00,000 and your total debt is ₹2,00,000, your net worth is ₹3,00,000.
Check your net worth every month or every few months. The aim is to see steady progress over time, not to become rich in a short period.
Follow a Simple Monthly Money Routine
A good money system should not feel hard to use. You can follow the same basic routine every month.
When your income arrives, divide it into your four money groups. Move your savings and investment amounts first. Then pay your bills and other essential costs. Make payments towards costly debt and keep track of what you spend.
At the end of the month, check your accounts and review your expenses. Update your savings total and net worth. Then make small changes to your plan if needed.
This routine can help you stay aware of your money without the need for complex tools or records.
Final Thoughts
A simple money system is not about avoid every expense or save every rupee. It is about use your income with care and give your money a clear purpose.
Start with the four main groups: needs, wants, savings and investments. Use separate accounts or clear records to manage them. Save money as soon as you receive your income, build an emergency fund and clear debt with high interest. Once your basic needs are safe, invest with care for your future.
You do not need to make big changes in one day. Start with one small step and follow it each month. Even a small amount of savings can make a difference when you stay consistent.
The best money system is one that is simple enough to follow every month. When you know where your money goes, you can make better choices, face sudden costs with more confidence and work towards a more secure future.
The goal is not just to have more money. It is to have more control over the money you already earn.