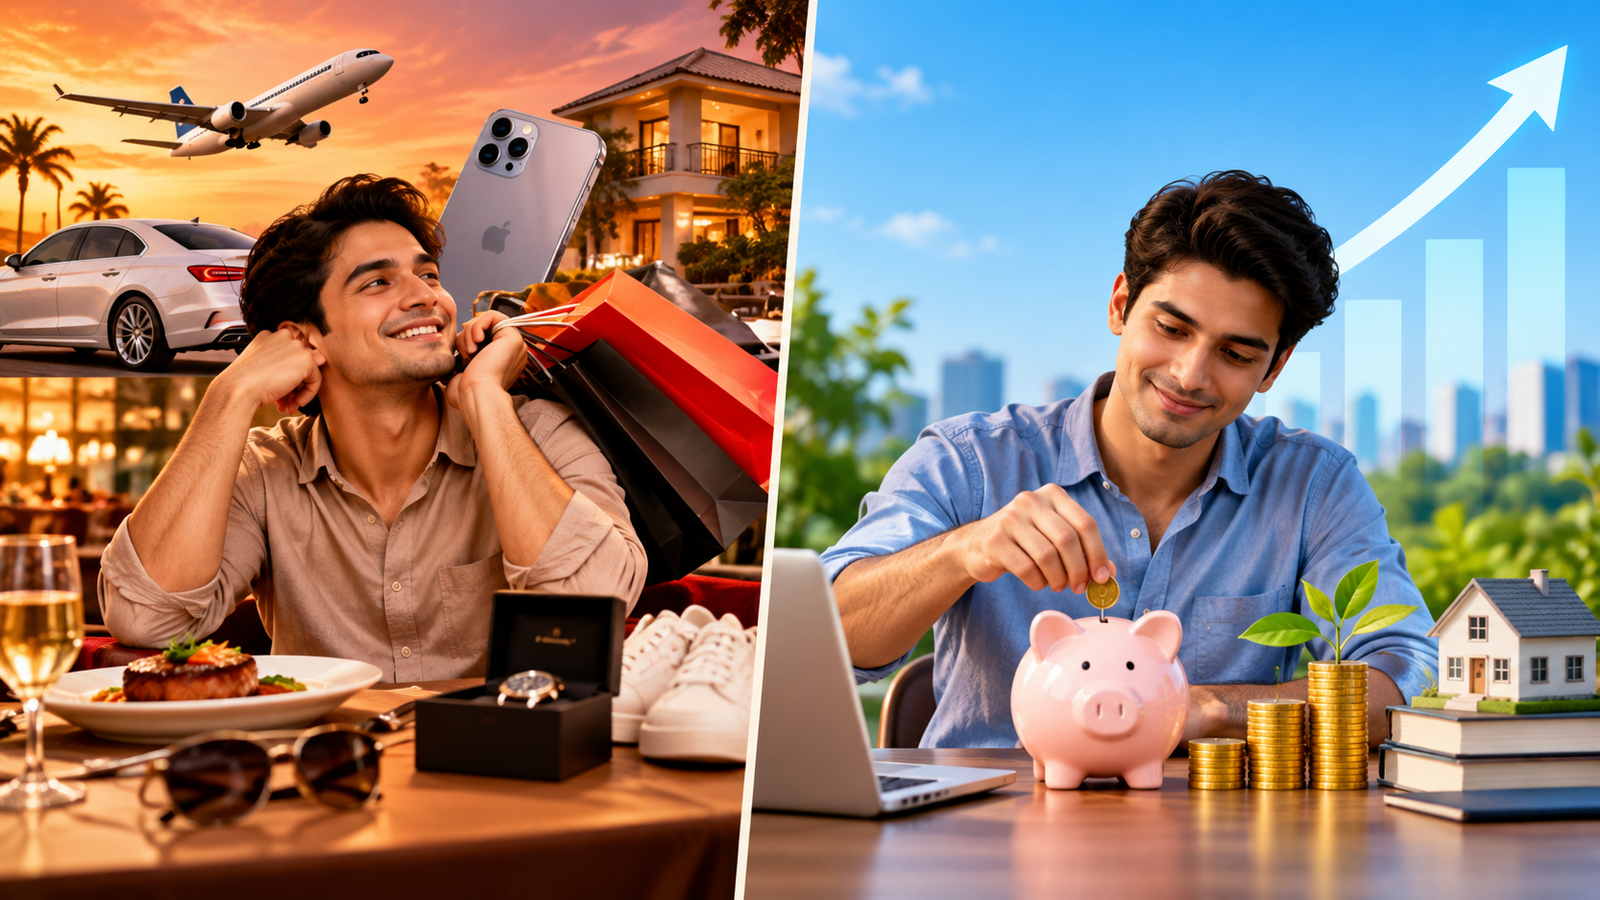
Lifestyle inflation happens when your expenses rise as your income grows. When you earn more money, you may start to buy better clothes, expensive gadgets, eat at costly restaurants, or choose a more expensive car. At first, these changes may seem small, but over time, they can take up a large part of your income.
For example, suppose your monthly salary rises from $3,000 to $4,000. You now have an extra $1,000 each month. Instead of saving or investing that extra money, you may spend it on things you did not need before. As a result, your income is higher, but your wealth does not grow at the same rate.
The main goal is simple: let your wealth grow faster than your expenses. You can enjoy a better life without the need to spend every extra dollar you earn.
1. Save Money Before You Spend
One of the best ways to avoid lifestyle inflation is to save a part of your income as soon as you receive it. Do not wait until the end of the month to see how much money is left.
Set aside a fixed amount for savings and investments first. Then use the rest for your daily needs and personal wants. This simple habit can help you stay within your budget and avoid wasteful expenses.
2. Follow the 50% Rule
Whenever your salary increases, try to save or invest at least 50% of the extra amount. You can use the other half to enjoy a better lifestyle.
For example, if your monthly income rises by $500, put $250 into savings or investments. Use the other $250 for things that make your life better.
This rule gives you a balance between your present needs and future goals. You do not have to give up every extra comfort just to save money.
3. Avoid Unnecessary Upgrades
A higher salary does not mean you must replace everything you own. If your phone works well, there is no real need to buy a new one just because you can afford it.
The same idea applies to cars, clothes, furniture, and other personal items. Before you buy something new, ask yourself whether your current item still does its job.
A simple choice today can save you a lot of money over time. Buy something better when you have a real reason, not just because your income allows it.
4. Make a Monthly Budget
A budget helps you understand where your money goes. Set a clear limit for your main expenses, such as rent, food, travel, bills, shopping, and fun.
Also, set aside a fixed part of your income for savings and investments. Try to follow these limits each month. If one expense rises, look for another area where you can spend less.
A budget does not mean you must stop all fun. It simply helps you use your money with care and avoid expenses that add little value to your life.
5. Do Not Compare Your Life With Others
It is easy to feel that you need better clothes, a bigger house, or a more costly car when you see what other people own. Social media can make this problem worse because people often share only the best parts of their lives.
But you do not know their income, debts, or financial problems. A person who looks rich may have very little money left after all their expenses.
Set your own goals and make choices based on what you can afford. Your financial success should not depend on how your life looks to others.
6. Keep an Emergency Fund
Life can bring sudden costs, such as medical bills, car repairs, or a loss of income. Without enough money set aside, you may have to use a credit card or take a loan to deal with these problems.
Try to keep an emergency fund worth three to six months of essential expenses. Keep this money separate from your daily budget and use it only for real emergencies.
This fund can give you peace of mind and protect your long-term financial plans.
7. Be Careful With Monthly Expenses
Some expenses may look small at first, but they can take a large part of your income over time. Rent, car payments, subscriptions, and memberships are common examples.
Before you agree to a new monthly payment, think about how it will affect your budget. A costly car loan or a much bigger home payment can reduce the money you have for other goals.
Keep your fixed costs under control. This gives you more freedom and makes it easier to save money each month.
8. Wait Before You Make Big Purchases
You do not have to buy something the moment you want it. Give yourself 48 to 72 hours before you make a major purchase.
During this time, ask yourself if you really need the item. Think about how often you will use it and whether it will make a real difference to your life.
Sometimes, the desire to buy something fades after a few days. This short wait can help you avoid poor choices and protect your money.
9. Use Extra Income to Buy Assets
When your income grows, use some of the extra money to build wealth. You can look at options such as index funds, retirement accounts, and other suitable long-term assets.
Before you choose an investment, learn about its risks and make sure it suits your goals. Do not put all your money into one place or follow advice just because someone else made a profit.
The aim is to let your money work for your future instead of spend it all on short-term wants.
10. Check Your Net Worth
Your net worth gives you a better idea of your financial health than your salary or the things you own.
It is the value of your assets minus your debts. Check it from time to time to see whether your financial position has improved.
Pay attention to how much you save, how much debt you repay, how much you invest, and how your net worth grows over time. These measures show real progress, even if you do not have a costly lifestyle.
A Simple Example of Lifestyle Inflation
Suppose your monthly income rises from $2,000 to $3,000. You now earn $1,000 more than before. You can use this extra money in a way that helps you enjoy life while also protect your future.
| Category | Before | After |
|---|---|---|
| Essential expenses | $1,000 | $1,100 |
| Lifestyle spending | $600 | $650 |
| Savings & investments | $400 | $1,250 |
| Total | $2,000 | $3,000 |
In this example, your income rises by 50%, but your lifestyle expenses rise by only $50. Your essential expenses rise by $100, while your savings and investments rise by $850.
This means you enjoy a small improvement in your daily life while a much larger part of your extra income goes towards your future. Over time, this choice can make a major difference to your financial position.
The Golden Rule: Grow Your Wealth, Not Just Your Expenses
Avoiding lifestyle inflation does not mean you must live a cheap or unhappy life. You can travel, enjoy good food, buy things you love, and spend money on experiences that matter to you.
The important thing is to know the difference between what you truly want and what you buy just because you have more money.
Do not let every salary increase lead to a bigger home, a new car, or more costly habits. Keep your needs under control, save a fair share of your income, and use extra money to support your long-term goals.
True wealth is not about how much money you spend or how rich you look. It is about how much financial freedom you have and how secure your future can be.