Life is full of surprises. Sometimes, you may face a medical emergency, lose your job, or need money for an urgent home repair. These events can affect your finances and create stress, especially when you do not have enough savings.
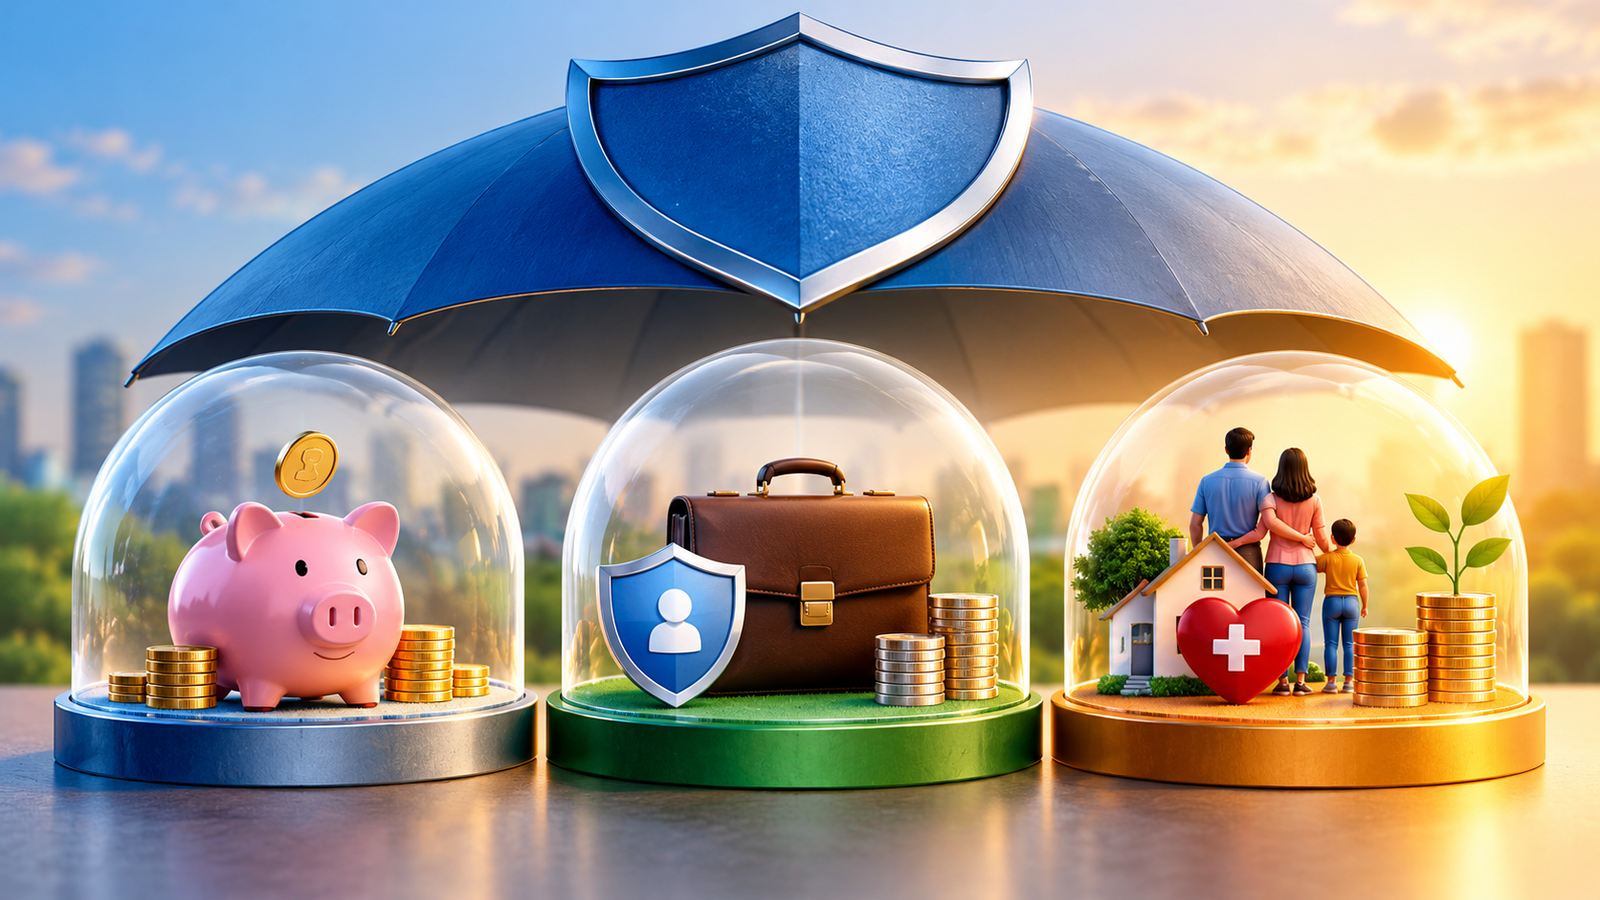
A financial safety net helps you stay prepared for such situations. It is a simple plan that protects your money, your family, and your future. Instead of keeping all your hopes on one savings account, you can build three layers of financial protection. Each layer has a different purpose and helps you deal with a different type of problem.
Layer 1: Build an Immediate Emergency Fund
The first layer of your financial safety net is an emergency fund. This is money that you can use when an unexpected expense comes up. It should be easy to access and should not be part of your regular monthly budget.
For example, you may need money for a sudden medical bill, urgent home or vehicle repairs, emergency travel, or a short break in your income. In such cases, your emergency fund can help you pay the bill without the need for a loan or credit card debt.
A good first step is to save between ₹10,000 and ₹25,000. You can also aim for an amount equal to one month of your basic expenses. The right amount will depend on your income and personal needs.
Keep this money in a savings bank account or another safe place where you can access it quickly. Avoid the use of risky investments for this part of your fund.
The main purpose of this layer is simple: you should have enough money to deal with small emergencies without disturbing your other savings.
Layer 2: Create an Income Protection Fund
The second layer protects you when your income stops or falls for a longer period. This can happen if you lose your job, your business faces a slow period, or a health problem stops you from work for some time.
Your immediate emergency fund may not be enough to cover several months of expenses. That is why you need a separate income protection fund.
Try to save enough money to cover at least three to six months of your basic living costs. If you are self-employed, have family members who depend on you, or have an irregular income, a reserve of nine to twelve months may be more suitable.
For example, if your basic monthly expenses are ₹15,000, your target should be between ₹45,000 and ₹90,000. If you spend ₹25,000 per month, aim for ₹75,000 to ₹1,50,000. For monthly expenses of ₹40,000, the target is ₹1,20,000 to ₹2,40,000. If your basic expenses are ₹50,000, you should aim for ₹1,50,000 to ₹3,00,000.
You can keep this money in a bank savings account, a fixed deposit with suitable early access, or another safe option with low risk.
This fund gives you time to find a new job, manage a business problem, or deal with a family emergency. It also helps you avoid debt when your regular income is not available.
Layer 3: Protect Your Future with Insurance and Investments
The third layer focuses on your long-term financial safety. It protects you and your family from major financial risks and helps you build wealth for future needs.
This layer has two main parts: insurance and long-term investments.
Insurance for Financial Protection
Health insurance is important because a major medical bill can use up years of savings. A suitable health insurance plan can help cover the cost of hospital care and reduce the burden on your family.
If your family depends on your income, term life insurance can also be useful. It can provide financial support to your loved ones if you are no longer there to provide for them.
You may also consider personal accident and disability cover. These plans can offer support if an accident affects your ability to work or earn money.
Choose insurance based on your needs, family size, income, and financial duties. Make sure you understand what the policy covers and what it does not cover.
Long-Term Investments for Future Needs
Once your basic safety funds and insurance are in place, you can focus on long-term wealth. This money may help you meet future goals such as retirement, your children’s education, or other major life needs.
You can consider retirement plans, diversified mutual funds, and long-term equity investments based on your risk level. You may also use suitable retirement savings options.
Do not use your emergency fund for risky investments. Long-term investments can rise or fall in value, so choose them with care and keep your future goals in mind.
The purpose of this layer is to protect your family from major losses and help you build a better financial future.
How the Three Layers Work Together
Each layer has a separate role. The first layer gives you quick access to cash for small and urgent needs. The second layer supports you if your income stops for a few months. The third layer protects your family from major risks and helps you build wealth over time.
For example, if your monthly basic expenses are ₹30,000, you can keep ₹30,000 as your first emergency fund. Your second layer can hold ₹1,50,000, which is equal to five months of basic expenses.
This gives you a total emergency reserve of ₹1,80,000, or six months of basic expenses. You can then build your insurance cover and long-term investments based on your needs and income.
Five Simple Rules to Maintain Your Financial Safety Net
1. Save Before You Spend
Set aside a part of your income as soon as you receive it. Even a small amount can help if you save it on a regular basis. Do not wait until the end of the month to see what money is left.
2. Keep Emergency Money Separate
Use a separate bank account for your emergency fund. This will help you avoid the use of that money for shopping, holidays, or other non-essential costs.
3. Choose Safe Places for Emergency Savings
Your emergency fund should be easy to access and should not face major market risk. Avoid shares or other risky assets for money that you may need at short notice.
4. Refill Your Fund After Use
If you use part of your emergency fund, make a plan to replace that amount. This will help you stay ready for the next unexpected expense.
5. Review Your Plan Every Year
Your expenses and family needs may change over time. You may get a new job, have a child, take a loan, or face higher living costs. Check your safety net at least once a year and adjust the amount when needed.
Make a Simple Plan Based on Your Expenses
The right emergency fund amount depends on how much you spend each month. First, work out your basic costs, such as food, rent, bills, travel, loan payments, and other important needs.
Next, decide how many months of protection you want. If your basic monthly expenses are ₹30,000 and your goal is six months, you need a total emergency fund of ₹1,80,000.
Now check how much you have already saved. Subtract that amount from your target. The rest is what you need to save.
For example, if you already have ₹30,000 and your target is ₹1,80,000, you still need ₹1,50,000. If you can save ₹5,000 every month, it will take you 30 months to reach your goal. This estimate does not include bank interest, inflation, or any change in your expenses.
Conclusion
A strong financial safety net does not need to be built in one day. Start with a small emergency fund, then create a larger reserve for income loss. After that, focus on insurance and long-term investments.
Each layer gives you a different type of protection. Together, they can help you face sudden expenses, deal with a loss of income, protect your family, and prepare for the future.
The most important step is to start with what you can afford. Save a little at a time, keep your money safe, and review your plan each year. A simple and steady approach can give you greater control over your finances and more peace of mind.