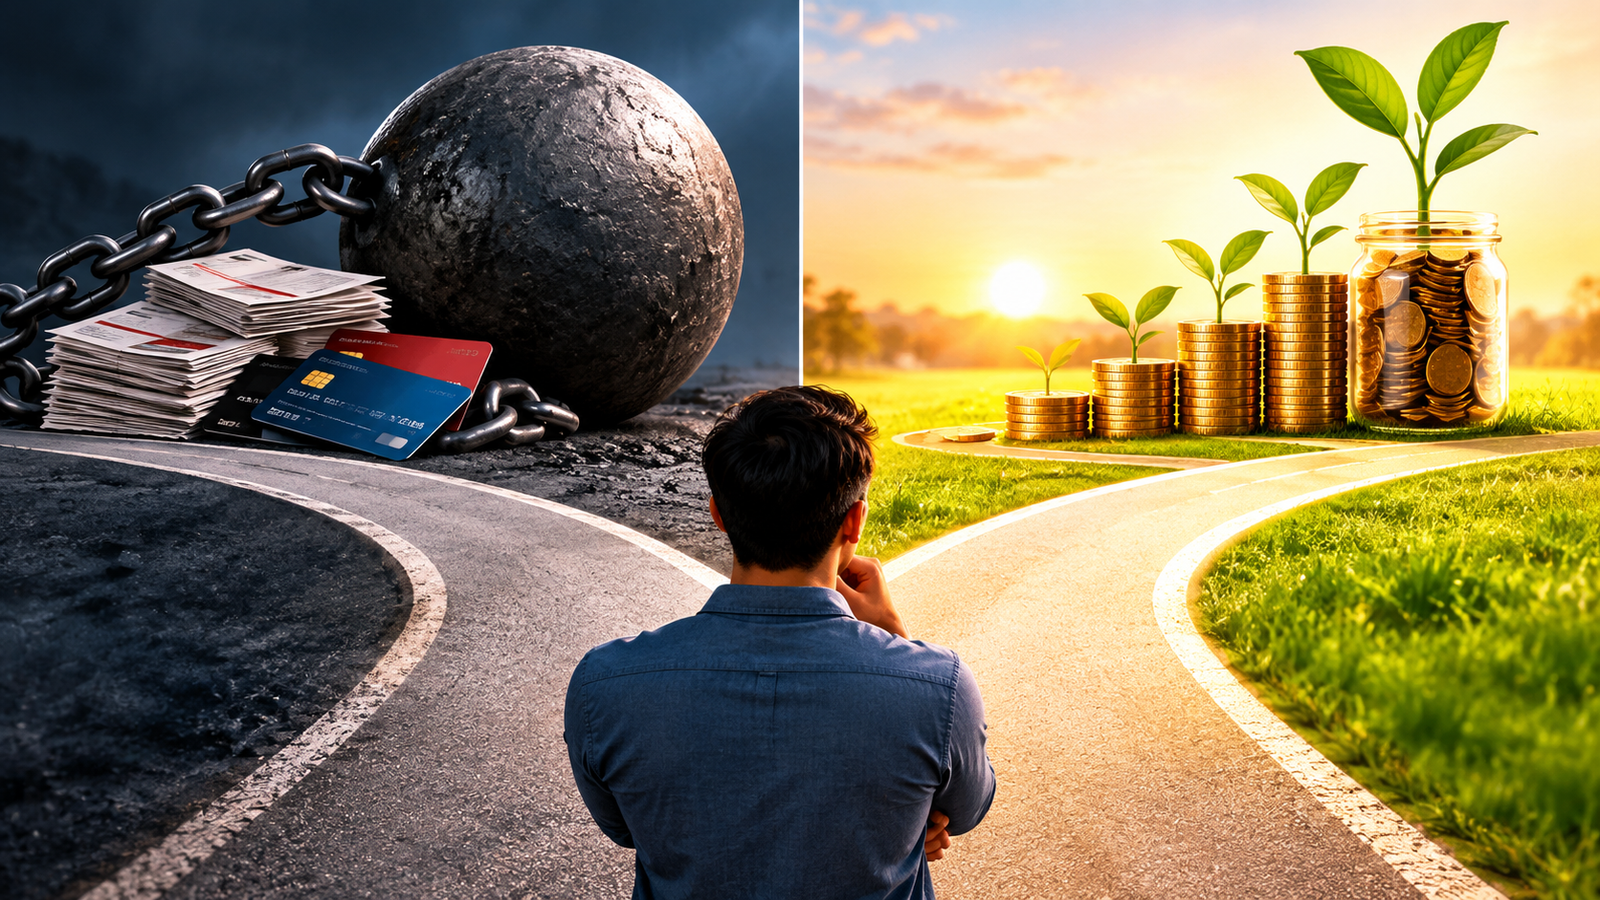
When you have extra money, you may face a common question: Should you pay off your debt or invest that money? Both choices can help you improve your financial future. However, the right choice depends on your debt, its interest rate, and your money goals.
In many cases, it is better to clear your debt before you invest. This is especially true when you have loans with high interest rates. The money you save on interest may be worth more than the profit you could earn from an investment.
Let’s understand when debt repayment is a better choice than investment and why it can help you build a stronger financial future.
1. When Your Debt Has a High Interest Rate
One of the main reasons to pay off debt first is a high interest rate. Some loans, such as credit card debt and personal loans, come with high interest costs. The longer you keep such debt, the more money you may have to pay.
For example, suppose your credit card charges 24% interest each year. At the same time, you expect your investment to earn around 10% per year. In this case, it makes more sense to clear your debt first.
Why? Because you can save 24% in interest on the amount you repay. However, your investment may earn only 10%, and that return is not certain.
Paying off high-interest debt can therefore give you a better financial result than an investment with a lower expected return.
2. When Investment Returns Are Not Certain
Every investment comes with some level of risk. Stocks and mutual funds may offer good returns over time, but their value can also fall. You may earn a profit one year and face a loss the next.
Debt is different. If your loan has a fixed interest rate, you know how much interest you must pay under its terms. This cost can take a large part of your income if you keep the debt for too long.
When you repay a costly loan, you reduce the interest you would otherwise have to pay. This gives you a more certain financial benefit than an investment whose return may change with the market.
For this reason, debt repayment can be a safer choice when your loan interest rate is higher than the return you expect from your investments.
3. When Monthly Loan Payments Use Too Much of Your Income
Large monthly loan payments can make it hard to manage your daily expenses. A major part of your salary may go towards EMIs, leaving you with less money for savings, family needs, and other goals.
When you clear some or all of your debt, you free up that money. You can then use it for your daily needs, future plans, or investments.
For example, if you pay off a loan with a monthly EMI of ₹10,000, that amount can become part of your monthly budget once the loan ends.
This can give you more control over your money and reduce financial stress. It can also make it easier to save for future needs.
4. When You Do Not Have Emergency Savings
Before you use all your extra money to repay debt or buy investments, make sure you have some money set aside for emergencies.
Life can bring sudden costs, such as medical bills, car repairs, or a loss of income. Without savings, you may have to borrow money again to meet these needs.
A good goal is to keep enough money to cover three to six months of essential expenses. This can help you manage a difficult situation without extra debt.
Once you have a basic emergency fund, you can focus more on debt repayment. This way, you do not have to choose between loan payments and unexpected expenses.
5. When Debt Interest Is Higher Than Expected Investment Returns
The interest rate on your debt can help you decide where your extra money should go.
For example, if your loan has an interest rate above 15%, it is usually better to focus on repayment. If the rate is between 10% and 15%, debt repayment should also be a major priority.
When the interest rate is between 6% and 10%, you may choose to divide your extra money between debt repayment and investments. If your debt rate is below 6%, investment may be a better choice, based on your goals and risk level.
These rates are general guides, not strict rules. Your decision should also depend on taxes, loan terms, investment risk, and how long you plan to keep your money invested.
The main idea is simple: Compare the interest you must pay with the return you may earn. If your debt costs more than your expected investment return, repayment is often the better option.
6. When You Want More Financial Security
Debt can create pressure, especially when you have several loans or large monthly payments. It may also make it harder to deal with sudden expenses or plan for the future.
When you become debt-free, you no longer have to worry about those loan payments. You can use more of your income for savings, family needs, and personal goals.
Being free from debt can also give you peace of mind. You may feel more confident about your money because fewer payments depend on your monthly income.
Of course, being debt-free is not the only way to build wealth. But if financial security matters more to you than the chance of a higher investment return, debt repayment can be a sensible choice.
7. A Simple Example: Debt Repayment or Investment?
Suppose you have ₹1,00,000 in extra money. You can either use it to repay a loan or invest it.
Your loan has an interest rate of 18% per year. If you repay ₹1,00,000, you could save ₹18,000 in interest over one year, assuming the full amount would otherwise remain unpaid for that year.
Now, suppose you invest the same ₹1,00,000 and expect a return of 12% per year. If you earn that return, your profit would be ₹12,000 before taxes.
In this example, debt repayment saves ₹18,000, while the investment may earn ₹12,000. The debt repayment offers a better result and avoids the market risk that comes with the expected investment return.
This shows why it can make sense to clear high-interest debt before you put extra money into investments.
Conclusion
Paying off debt before you invest can be a smart financial choice, especially when your loans have high interest rates. It can reduce your interest costs, free up your monthly income, and give you more control over your money.
However, do not ignore emergency savings. Keep enough money aside for basic needs and unexpected costs before you make large extra loan payments.
Once your high-interest debt is under control, you can focus more on long-term investments and other financial goals.
The aim is not just to become debt-free or earn more from investments. It is to build wealth, protect your money, and create a future with less financial stress.
ALSO READ: Bitcoin Halving and Its Effect on Supply Economies