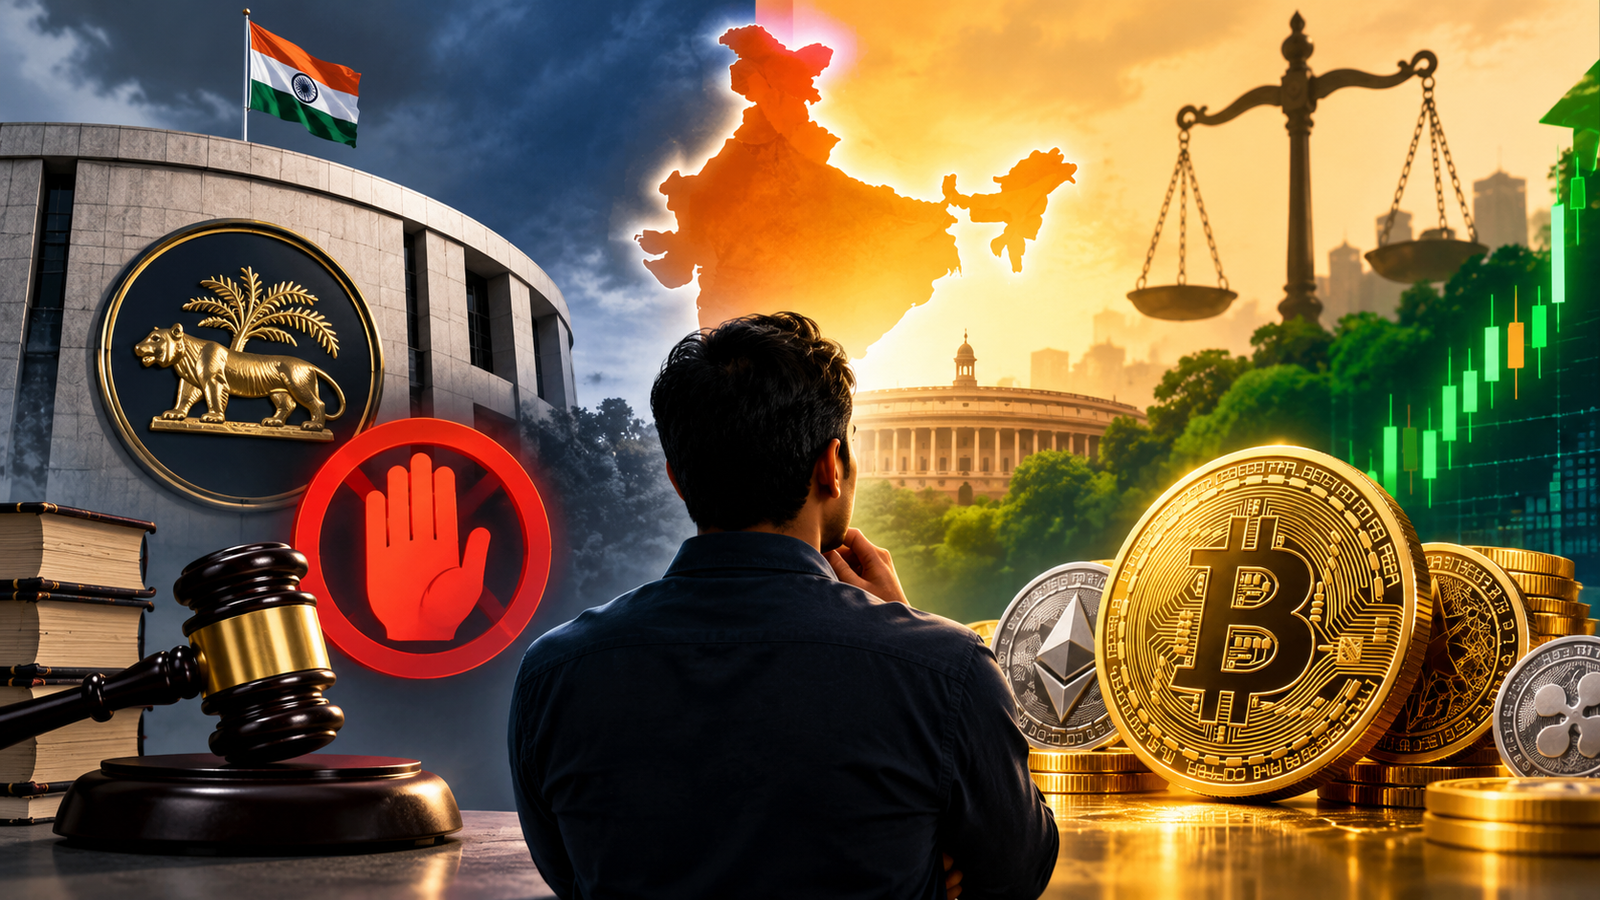
India’s approach to crypto remains caught between taxation, enforcement and the lack of a clear legal framework. The country has not passed a complete law that either permits crypto as a regulated financial asset or bans it outright.
At the same time, recent actions from the Reserve Bank of India (RBI), the Financial Intelligence Unit-India (FIU-IND), the Finance Ministry and Parliament show that the government is not ignoring the sector.
The latest signals point in different directions. The RBI remains strongly opposed to crypto’s role inside the formal financial system. Parliament has examined the idea of a limited regulatory framework. The government continues to tax crypto activity. At the same time, the FIU has taken direct action against offshore and domestic platforms that fail to meet anti-money laundering rules.
For investors, this creates an important distinction: crypto can exist in India without receiving the same legal protection as a regulated financial product.
The RBI Remains Concerned About Crypto
The RBI has maintained a cautious view of virtual digital assets, or VDAs. In July 2026, the central bank told the Parliamentary Standing Committee on Finance that it did not support the treatment of VDAs as currency. It also did not give a clear answer on whether some VDAs could fall under securities regulation.
The RBI’s broader position is even more restrictive. Documents reviewed in July showed that the central bank still preferred a crypto policy that leaned toward prohibition. The RBI has also raised concerns about privately issued stablecoins and the possible effect of crypto on financial stability and monetary sovereignty.
This does not mean India has banned crypto. That distinction matters.
The RBI’s view is a policy position, not a new law. Investors therefore should not treat every strong statement from the central bank as proof of an immediate nationwide ban.
Parliament Is Looking at a Different Route
While the RBI has called for strong limits, the Parliamentary Standing Committee on Finance has examined a more gradual route.
In July 2026, the committee recommended an interim framework based on recognised self-regulatory organisations, or SROs. Such a system could operate under the supervision of an appropriate regulator until India has a dedicated law for VDAs.
The committee also called for clearer definitions because different types of digital assets may not fit neatly into one legal category.
This is an important signal, but it is not the same as new regulation.
The committee has been studying VDAs and their future treatment. Its work also includes questions about crypto investment products, tokenised securities and the possible role of existing securities law. The Finance Committee had another session with the Finance Ministry’s Department of Economic Affairs on September 16, 2026, as part of its study of VDAs and the way forward.
For investors, the message is simple: India is still deciding how different digital assets should fit into its legal system.
Tax Does Not Mean Government Approval
One of the biggest sources of confusion is India’s tax treatment of crypto.
Crypto transactions are subject to tax rules, including a 30% tax on gains. There is also a 1% tax deducted at source on certain crypto transactions. These rules show that the government recognises that crypto activity takes place and wants to bring it within the tax system.
But taxation should not be confused with approval.
A government can tax an activity without giving it the status of a regulated investment product. A person may have tax obligations from a transaction even when the underlying asset does not have the investor protections associated with shares, bonds or bank deposits.
This difference is especially important for new investors. Paying tax on crypto does not mean that the government has certified a particular token, exchange or investment scheme as safe.
FIU Action Shows Where Enforcement Is Already Clear
If the broader crypto policy remains uncertain, the anti-money laundering side is much clearer.
On September 9, 2026, the FIU-IND issued notices against 15 VDA service providers for non-compliance with the Prevention of Money Laundering Act, or PMLA. The list included Weex, Blofin, Rezorex, Bitunix, DigiFinex, Toobit, XT.com, Latoken, WOO X and Pionex, among others.
The government said these platforms were required to register with FIU-IND as Reporting Entities if they carried out activities such as crypto-to-fiat exchange, crypto transfers or custody-related services for users in India.
The rule applies based on the activity of the service provider, not simply on whether the company has a physical office in India. Both offshore and onshore VDA service providers can fall within these requirements.
This is one of the clearest lessons from recent events. An overseas location does not automatically place a crypto platform outside Indian compliance requirements.
FIU Registration Is Not a Safety Certificate
There is another important distinction.
If a crypto platform registers with FIU-IND, that does not mean the government has approved all of its products. FIU registration relates to obligations under the money laundering framework. It does not automatically turn crypto into a regulated security or give investors the protections they may receive in traditional financial markets.
The Finance Ministry has also warned that crypto products and NFTs remain unregulated and can carry high risks. It has said that users may have no regulatory recourse for losses from such transactions.
This means investors need to look at two separate questions.
The first is whether a platform meets its legal compliance duties. The second is whether the asset itself has a clear regulatory status and investor protection framework.
Those questions are not the same.
Stablecoins Could Face Extra Pressure
Stablecoins are another area where policy signals deserve attention.
The RBI has expressed concern about stablecoins backed by foreign currencies because they could affect monetary sovereignty and the wider financial system. It has also raised concerns about rupee-backed stablecoins, including their possible effect on the government’s income from issuing fiat currency and on financial stability during periods of market stress.
This does not amount to a blanket stablecoin ban.
It does show, however, why investors should avoid assuming that all crypto assets will receive identical treatment in a future Indian framework. A stablecoin used for payments could raise very different regulatory questions from a token that represents an investment, a utility token or a tokenised security.
Offshore Exchanges Are a Major Policy Problem
Offshore platforms have become an important part of India’s crypto market. Government officials have raised concerns that transactions through overseas exchanges and private wallets are harder to track for tax purposes.
India had almost 39 million crypto traders who held about $2.1 billion in digital assets at the end of May 2026, according to figures reported in July. The tax department had also found cases of crypto holdings that were not properly reported.
Offshore exchanges accounted for about 91.5% of India’s crypto trading volume in FY2024–25, while FIU-registered Indian exchanges accounted for 8.5%.
These figures help explain why enforcement has become important for policymakers. If a large share of activity takes place through overseas platforms, Indian authorities face greater difficulty with tax reporting, ownership records and compliance checks.
What Investors Should Not Assume
The current policy signals do not support the conclusion that India is about to ban every cryptocurrency. They also do not support the opposite conclusion that India is about to fully legalise crypto as a normal financial asset.
The evidence points to a more complicated path.
India is likely to continue its focus on tax compliance and anti-money laundering rules while policymakers debate the wider legal status of VDAs. Different assets may eventually receive different treatment. Securities, stablecoins, payment-related tokens and other forms of crypto may not fit under one common set of rules.
For investors, this means the absence of a full crypto law should not be mistaken for the absence of regulation altogether.
The Real Policy Gap
India’s crypto policy gap is not simply about whether crypto is legal or illegal.
The bigger issue is the difference between permission to participate in an activity and protection within that activity.
A person may buy and hold crypto. A platform may meet FIU requirements. A transaction may create a tax obligation. Yet none of those facts alone means that the asset has the same legal status as a listed share or a regulated financial product.
That is the most useful way to read India’s recent signals.
The RBI continues to warn about financial and monetary risks. Parliament is examining a possible regulatory structure. The Finance Ministry continues to collect taxes and strengthen compliance. FIU-IND is taking action against platforms that do not meet PMLA requirements. At the same time, there is still no comprehensive crypto statute that settles the status of every major type of digital asset.
Until that gap closes, investors need to separate tax treatment, AML compliance, platform access and legal protection. They are four different things.
The clearest conclusion from the latest signals is therefore not that India has chosen a final crypto policy. It is that the country is becoming more active in controlling the risks around crypto while the larger question of its place in the financial system remains open.